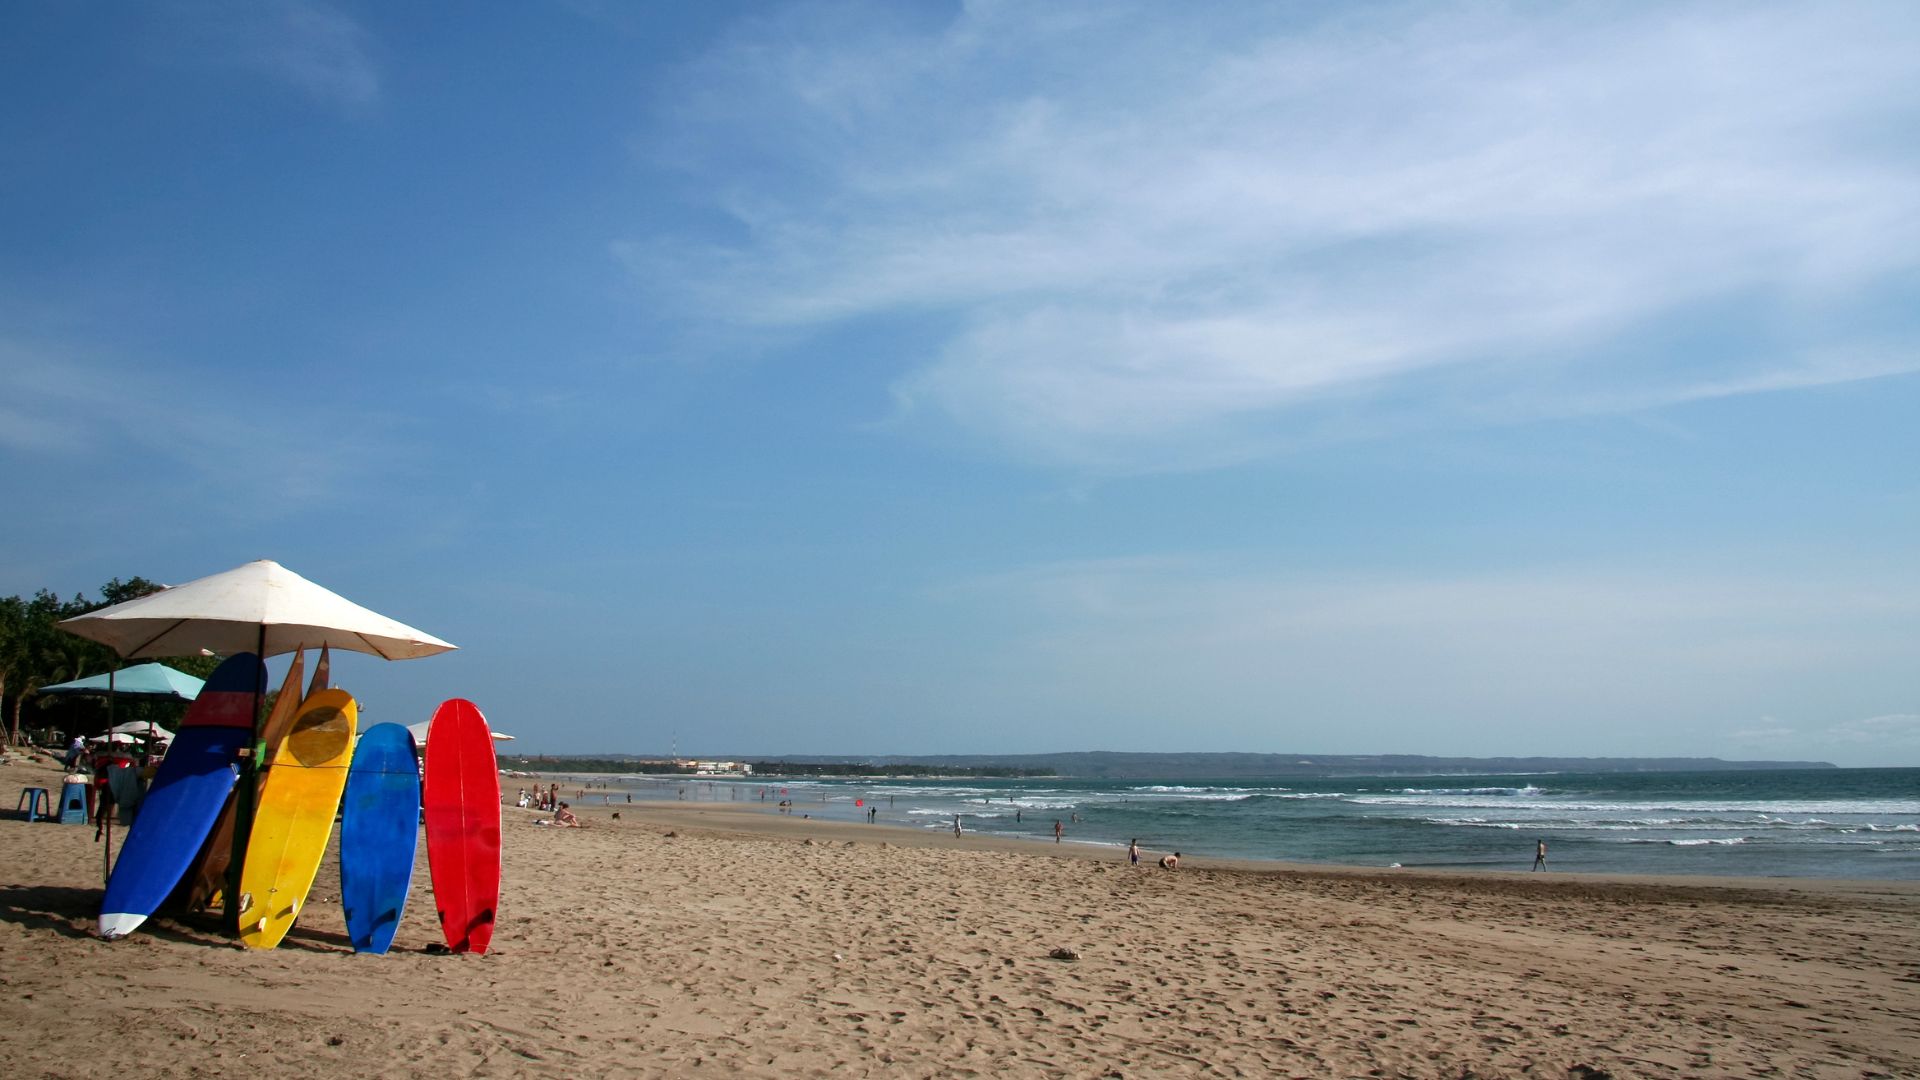
A surf trip through Indonesia — from remote breaks to a Jakarta layover — shows why travel insurance covers you at every stop.
I grew up in Indonesia — born in East Java, with many vacation days surfing (for fun, not professional) in Bali as a kid on family vacations back in the 70s and 80s, then graduating from Jakarta International School in 1986. Bali and Jakarta couldn’t feel more different: quiet beach towns and reef breaks on one side, traffic and skyscrapers on the other. But looking back, neither one felt more “dangerous” than the other. They were just different parts of the same trip, and each came with its own risks.
That’s still true for anyone chasing waves overseas today. Picture a few days surfing off Sumatra, then a stop in Jakarta or Singapore before the flight home — nothing extreme, just a normal trip with a surfboard bag and a 3-day layover. It’s easy to assume the remote stretch is the “risky” leg and the big city stop is the safe one where nothing much could go wrong.
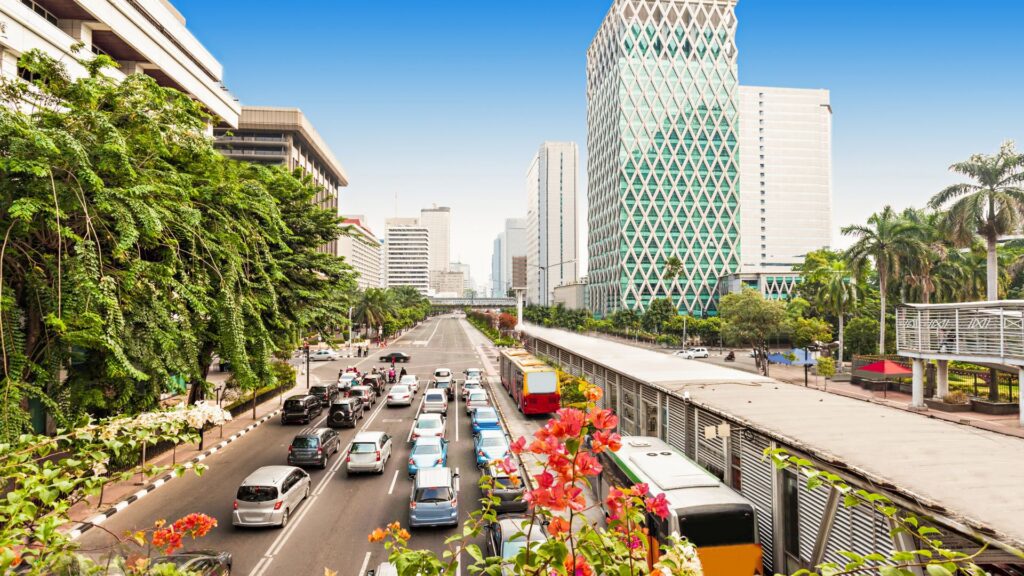
That assumption is where a lot of travelers get it backwards. Medical care can be harder to reach on a remote coastline, and a bad wipeout or reef cut is a real possibility out there. But cities carry their own risks too — traffic accidents, food-borne illness, a bad fall on uneven sidewalks, a delayed or cancelled flight. None of that requires anything extreme to happen; it can happen on an ordinary afternoon in a modern, familiar-feeling city. Interesting tidbit: according to a recent UN report, Jakarta’s metro area was listed as the world’s most populous at the time of this writing. I wouldn’t have guessed that back in the mid-80s, when I rode my motorcycle around the city running errands for my dad on weekends and heading to school during the week.
That’s exactly why travel insurance isn’t something you turn on for the “adventurous” leg of a trip and skip for the rest. A properly selected travel medical plan may cover you for the eligible portions of your trip, subject to the plan’s coverage dates, geographic area, exclusions, and other terms— remote surf camp, connecting flight, or a few days of city sightseeing in between.
The right plan still depends on your itinerary — how remote you’re going, how long you’ll be gone, what kind of sports you may be enjoying, and what you’ll be doing while you’re there. That’s worth working through before you buy, rather than guessing — browse our travel insurance plans to see what fits a trip like this, from single-destination coverage to multi-stop itineraries.
If you want the fundamentals explained in plain language before you buy, our video walkthrough on understanding your travel insurance is a good next stop.
Quick Q&A
Do I need travel insurance if part of my trip is just a stopover in a big city like Jakarta or Singapore?
Yes. Travel insurance generally applies across the eligible portions of your trip, rather than only to the most remote or adventurous destination, subject to the plan’s coverage dates, geographic area, and terms. A stopover in a major city still carries real risks (traffic accidents, illness, lost luggage, flight disruptions), and a properly selected travel medical plan may provide benefits across the eligible portions of your itinerary, not just the “adventurous” segment. Browse our travel insurance plans to see how coverage applies across a mixed itinerary.
Does a standard travel insurance plan cover surfing or other outdoor activities?
It may be covered, but recreational surfing is not treated identically under every travel medical plan. But coverage isn’t identical across every plan: some carriers limit or exclude certain sports, so it’s worth confirming your coverage details with an advisor before you go. That can affect which travel medical plan fits best.
Many of our plans cover a wide range of sports, and for any specific activity you have in mind, we check directly with our underwriters to confirm the best option for you. Since GNI was founded in 1997, we’ve learned that carrier benefits change constantly — as we like to say, change is always in the air — so let us verify the details rather than guess. Connect with us and we’ll help you find the right plan.
Whether your trip is all remote coastline, all big city, or a mix of both like this one, request a quote and we’ll help you compare options based on your actual itinerary.
Benefits, exclusions, eligibility rules, coverage limits, lookback periods, coverage area, restricted or excluded countries, and pre-existing condition provisions can vary by carrier and plan—and may change over time. As we like to say, change is always in the air, so use the guidance above as a helpful starting point, not a guarantee of coverage. Good Neighbor Insurance advisors can help explain available options and application requirements; however, the insurance carrier makes the final decisions regarding eligibility, underwriting, policy issuance, exclusions, benefits, premium rates and payment requirements, and claims under the policy.
Insurance plan details and insurance company processes may change from time to time. Please connect with one of our GNI international insurance advisors for the most current information.